


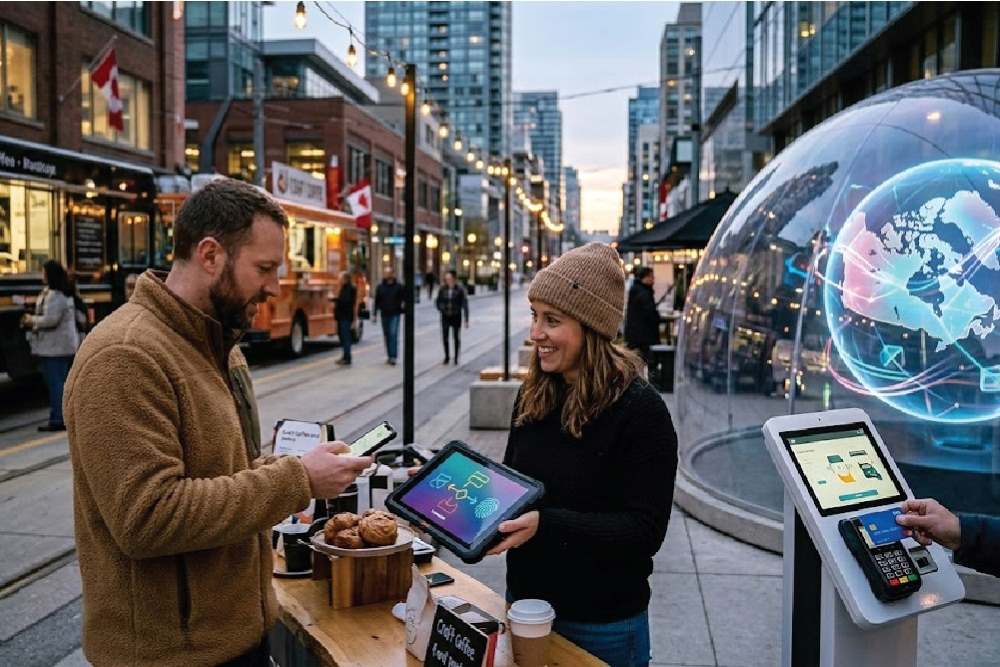


Payments used to sit at the end of a sale. Today they are part of the customer experience, the accounting process, fraud prevention, cash forecasting, and even lending. Canadian businesses are moving toward a payment environment where the method matters less than whether money can move securely, quickly, and with useful information attached.
Customers Expect One Experience Across Channels
A customer may discover a business on social media, place an order online, pick it up in store, and request a refund later. Payment systems have to follow that journey. Businesses that operate separate tools for e-commerce, in-store sales, invoices, and mobile service can end up with fragmented reporting and more manual reconciliation.
Faster Settlement Can Change Small-Business Cash Flow
The speed at which funds become available matters most to businesses with narrow cash cushions. Quicker settlement and real-time payment capabilities can reduce the period during which a completed sale is still economically unavailable. The benefit extends to supplier payments, payroll, insurance disbursements, and business-to-business transactions.
Speed, however, reduces the time available to catch mistakes. Strong authentication, confirmation steps, limits, and monitoring become more important when a fraudulent payment can leave almost immediately.
Data Will Travel With the Payment
The future is not only faster money; it is better information. A payment that arrives with structured invoice data can be matched automatically, reducing bookkeeping and improving cash visibility. For companies handling hundreds of supplier or customer transactions, that can save more time than the payment speed itself.
Open Financial Connections Could Increase Choice
Secure data sharing may make it easier for businesses to connect banks, accounting platforms, lenders, and payment providers without relying on fragile workarounds. If implemented well, this could improve competition and reduce the effort required to switch services. The risks—privacy, cybersecurity, and vendor dependence—will need equal attention.
Payment Choice Will Still Matter
The future will not belong to one method. Cards, mobile wallets, account-to-account transfers, invoices, and cash will coexist because customers and industries have different needs. Businesses should resist designing payment policy around technology fashion alone. Reliability, cost, customer preference, and contingency planning all matter.
Merchants Need More Transparency, Not More Complexity
As payment systems become more sophisticated, pricing can become harder to understand. Processing fees, chargebacks, hardware, software, gateway costs, and settlement terms should be evaluated together. A platform that offers useful integration may justify a higher headline rate, but businesses need enough transparency to know what they are paying for.
Resilience Will Matter as Much as Speed
A modern payment strategy needs a plan for the moments when the preferred system is unavailable. Networks fail, terminals break, credentials are compromised, and customers sometimes use a method the business did not expect. Companies that depend on one channel should decide in advance how they will continue taking orders, issuing refunds, and reconciling transactions during an interruption. Payment resilience is also an accounting issue. Faster money is useful only if the business can identify what arrived, which invoice it belongs to, what fees were deducted, and whether the settlement matches the sale. As more methods are added, reconciliation can become the hidden operational cost of convenience. That creates an opportunity for better integration. Businesses should value payment tools that reduce manual matching, surface exceptions quickly, and provide usable reporting rather than simply adding another checkout button. The system that saves a few seconds for the customer but creates hours of back-office correction is not truly efficient. Security controls should evolve with convenience. Staff permissions, refund limits, device management, multifactor authentication, and clear escalation procedures can reduce the damage from a compromised account. Payment innovation is strongest when a faster customer experience is matched by slower, deliberate thinking about control.
Payment strategy should also include the people who handle exceptions. A refund that fails, a duplicated charge, a disputed transaction, or a settlement that does not arrive can quickly become a customer-service issue and an accounting issue at the same time. Staff need simple escalation paths and enough information to solve the problem without passing the customer between departments. As payment options multiply, ownership becomes important: someone should know which provider is responsible for each part of the flow, where reports are stored, and how an outage is communicated. Businesses should also avoid measuring success only by transaction speed. Reliability, acceptance rates, fraud losses, support quality, reconciliation time, and total processing cost are equally useful. The best payment experience is often the one customers barely notice because it works consistently. Behind that simplicity, however, should be disciplined controls and clear contingency plans. Innovation is valuable when it removes friction without making the financial process harder to understand or recover when something goes wrong. Payment teams should document who owns merchant support, disputes, refunds, settlement review, and outage communication. That clarity prevents small exceptions from bouncing between departments while customers wait and accounting records drift. It also helps management judge whether a provider is truly saving time or simply moving work elsewhere. The future of payments will reward businesses that combine speed with resilience, clear records, useful data, and enough control to recover when systems fail.
Canada’s payment future will be judged by whether it makes commerce easier without concentrating too much control in a few systems. For businesses, the winning setup will combine speed, resilience, usable data, security, and customer choice. Payments are becoming infrastructure, and infrastructure should work even when the newest feature does not.


